 Skip to content

A rental property can face extra risks during a void period, even when you don’t yet know what happens next. Unoccupied property insurance may address changes in cover, but check the conditions of your empty property insurance before relying on it.
A gap between tenants, delayed repairs or an unsettled tenancy can each need different handling. Your own policy wording should guide the plan.
Start by confirming when your insurer considers the property unoccupied, what remains covered and who will carry out the required checks.
Key Takeaways
- Check your policy’s definition of an unoccupied property and when any restrictions begin. Limits vary, and a visit may not count as occupation or restart the vacancy period.
- Tell your insurer or broker as soon as you know the property will be empty. Explain its condition, likely vacancy, planned work and who still has a right to occupy, then keep any changes to the cover or conditions in writing.
- Follow the policy’s inspection, heating, water and security requirements. Agree who is responsible for each task and keep dated records of visits, repairs and access.
- Confirm what the policy covers, including exclusions, limits and excesses, before relying on it. Get separate confirmation for renovation work, and don’t treat insurance precautions as permission to enter or clear belongings.
When does a property count as unoccupied?
The date the tenant leaves matters. So does the insurer’s definition of occupation, which may include whether the property remains furnished.
Check the consecutive-day limit
The ABI explains that home insurance cover may be restricted after a property has been empty for a prolonged period, often 30 or 60 days. These are examples, not a deadline shared by every policy.
Read the definition in your insurance policy alongside the schedule and any endorsements, which change the standard terms. Check whether restrictions begin immediately or after a stated number of consecutive days. Check the wording for a second home or holiday home, as occupancy definitions may differ.
Homeprotect’s published definition includes properties recorded as unoccupied, unfurnished properties and those not lived in for more than 30 consecutive days.
Don’t assume visits restart the clock
A viewing, contractor visit or inspection doesn’t necessarily count as occupation. Ask your insurer what qualifies before treating any visit as a break in the vacant period.
Keep the tenant’s departure date and expected vacancy length recorded. If the return date is uncertain, say so.
The insurance definition is separate from the tenancy position. Empty rooms and unanswered messages don’t establish that you have lawful possession.
Tell the insurer before the vacancy begins
Contact your insurance provider or broker as soon as you know the property will become empty. You don’t need a complete refurbishment or re-letting plan before making contact.
Explain the property as it stands
Give the vacancy date, likely duration, current condition and any planned work. Explain whether furniture remains, utilities are connected and anyone still has a right to occupy.
Ask whether your existing landlord insurance, including any buildings insurance, can continue, as terms depend on the insurer and policy. Confirm whether cover will change or specialist cover is needed. Get the response and any new conditions in writing.
For planned work, ask whether renovation insurance or another arrangement is needed before work begins.
If the tenancy remains unresolved, make that clear. An insurance conversation doesn’t authorise entry, lock changes or removal of belongings.
Report later changes as well
Check the policy’s notification duties for damage, security failures, building work and a vacancy that lasts longer than expected. Also ask when to report a new tenant moving in.
For a probate property, tell the insurer about the death and confirm who can manage the policy.
Commercial landlords should check their own vacancy terms. RICS advises confirming whether existing cover continues and on what basis, rather than assuming every vacancy requires a replacement policy.
Inspection frequency and records need an agreed owner
A property can deteriorate between visits without anyone noticing. A small leak, damaged lock or failed heating system can lead to property damage if no one reports it promptly.
Follow the schedule in your policy
Don’t borrow an inspection timetable from another landlord. Requirements for regular inspections, whether weekly, fortnightly or less often, depend on the policy and type of cover.
Homeprotect’s published conditions require inspections at least every 14 days for its “Unoccupied” and “Unoccupied Plus” cover. Its “Temporarily Unoccupied” arrangements have different requirements.
Name the person responsible and arrange cover for holidays or illness. If the required visits aren’t practical, discuss this with the insurer before a gap occurs and ask whether specialist cover is available.
Ask whether an agent or property manager can inspect on your behalf, and what each inspection must include.
Make the record useful
Record the date, time, visitor, areas checked, concerns found and action taken. Note when nothing has changed as well.
Homeprotect requires records for those unoccupied cover types to be made during the inspection or within 24 hours.
Keep dated photographs, repair invoices and contractor reports together. Check entry points, visible water damage, heating where required and external conditions.
Never send someone into an unsafe building to complete an inspection. Record the concern and arrange an appropriate response.
Heating, water and winter conditions
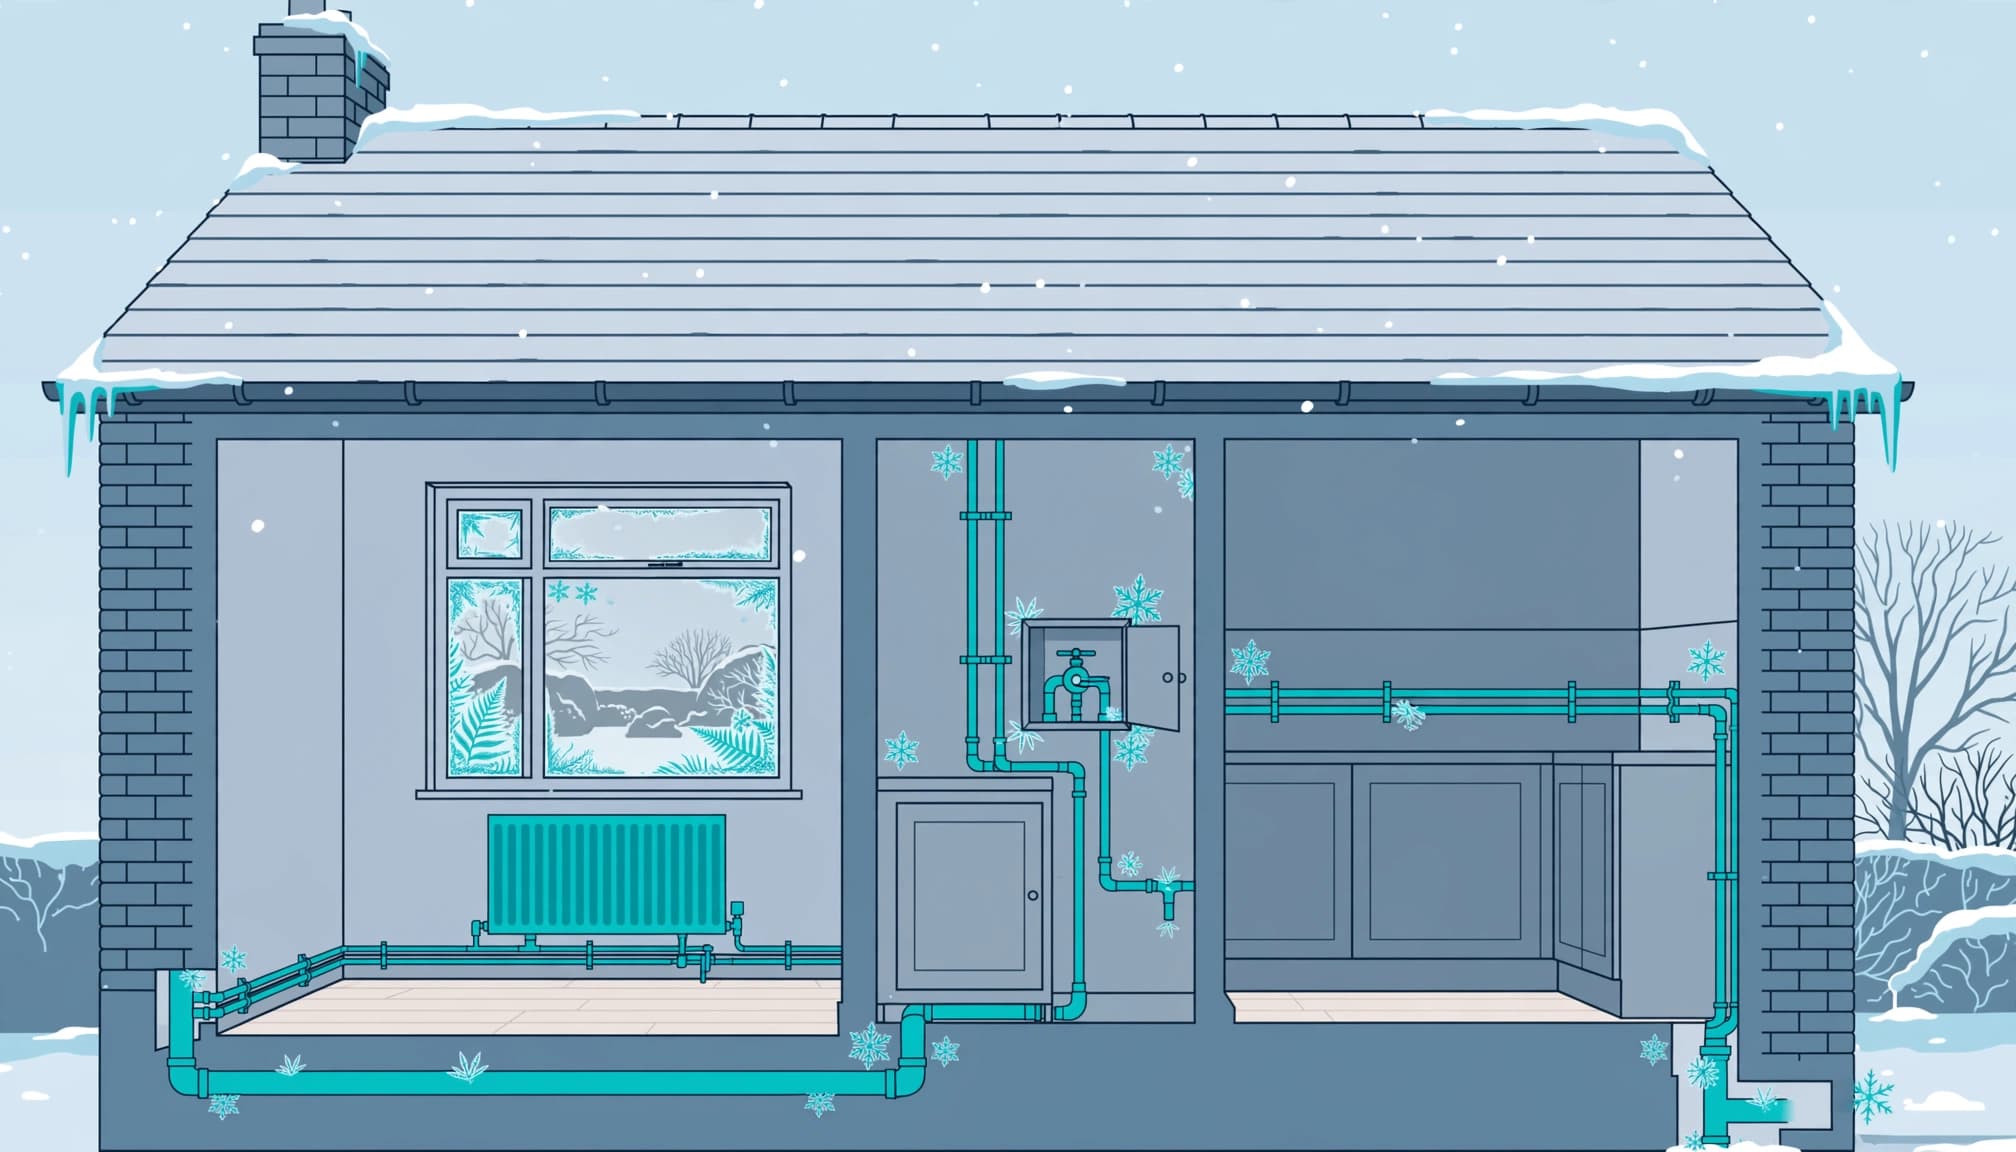
Cold weather needs attention before the property is left empty. Burst pipes can release water that goes unnoticed until the next visit, causing property damage.
Confirm what must remain switched on
Check whether the policy requires heating, a minimum temperature, particular settings or additional winter inspections. Don’t assume a boiler’s frost setting meets the insurer’s requirement.
Agree who will check the system and what happens if it fails. If heating must remain on, the electricity or fuel supply needs to support that plan.
Winter dates also vary. Ask whether seasonal restrictions apply to escape of water, even where the building is inspected.
UKinsuranceNET’s guidance on water damage in empty properties explains why unattended leaks need particular attention.
Check isolation and draining requirements
Some policies require the water supply to be isolated and systems drained. Others allow different arrangements. Confirm the precise requirement before turning anything off.
Ask a qualified person how to leave boilers, sprinkler systems and shared supplies safely. Closing a stopcock isn’t necessarily the same as draining the system.
Homeprotect states that escape of water is excluded throughout the year under its “Unoccupied” and “Unoccupied Plus” cover.
Water precautions reduce the risk of damage. They don’t restore escape-of-water cover where the policy excludes it.
Keep a record of the work and who completed it.
Security conditions start with sound entry points
Check the policy’s security measures for locks, doors, accessible windows, alarms and outbuildings. Repair broken glazing and doors that don’t close securely before relying on extra monitoring.
Confirm your authority before changing locks. Where a tenancy remains unresolved, seek qualified advice. Safety work doesn’t give you possession.
Ask whether alarms must remain active, monitored or maintained. If you plan to use a temporary wireless alarm, check whether the insurer accepts it.
Agree who will respond to alerts or security faults. A notification on an unattended phone leaves a practical gap and can increase the risk of property damage.
For larger, exposed commercial sites, security doors, shutters or monitored CCTV may be proportionate. Discuss proposed measures with the insurer and suitable contractors. Keep required exits usable.
Check whether the wording also requires mail removal, garden maintenance or removal of combustible waste. These tasks may help reduce exposure, but they don’t replace required locks or inspections.
Keep an access record for keys, alarm fobs and contractor visits. Record who receives replacement keys after an authorised lock change.
Check what empty property insurance actually covers
A policy described as empty property insurance or unoccupied property insurance doesn’t tell you what it covers. Read the terms and conditions, insured risks, exclusions, limits and excesses together.
Check whether buildings insurance covers property damage from storm, flood and escape of water, as well as theft and vandalism or malicious damage. Ask about conditions attached to each risk, including forced-entry requirements where relevant.
Insuristic’s unoccupied home insurance overview describes the gap that can arise when standard home insurance reaches its vacancy limit. Check whether vacant property cover is needed, and assess any replacement policy on its own terms.
As a property owner, confirm public liability and any restrictions on rent-related cover. Don’t assume loss-of-rent insurance pays for an ordinary gap between tenants.
Check how buildings and contents are treated, especially where furniture or appliances remain. For a flat, ask the managing agent about the block policy and check how it works with your separate landlord policy.
Compare specialist cover quotations using the same rebuilding sum insured, vacancy details and proposed work. A lower premium may come with narrower protection or a larger excess.
A missed condition or undeclared change can affect a claim. The outcome depends on the wording and circumstances.
Renovation and building work need separate confirmation
Tell the insurer what work is planned before it starts, and ask whether renovation insurance is required for the proposed scope. “Renovation” can mean decorating one room or removing part of the structure, and those jobs raise different questions.
Describe the agreed scope, dates, contractors and any changes to the roof, walls, plumbing or electrical systems. Explain whether the building will remain weatherproof and secure throughout.
Ask about structural work, hot work such as welding, scaffolding and periods when doors or windows are removed. Check whether the policy restricts any of these activities or requires specialist cover.
Contractor insurance doesn’t automatically cover every risk to your building. Confirm who provides buildings insurance for the existing structure, and what renovation insurance covers for the work and materials stored on site.
Keep the contractor’s insurance details, quotation and agreed changes with the property records. If the scope expands, contact the insurer again before the additional work begins.
Describe clearance and cleaning accurately. They shouldn’t be treated as permission for demolition, specialist hazard removal or unapproved building work.
Put clearance and access into the same written plan
A vacant property may still contain belongings that matter. Insurance precautions shouldn’t become a reason to clear everything before authority and ownership are settled.
For an unresolved tenancy, preserve belongings and seek advice on the lawful process. For probate, agree decisions with the executor or authorised representative. Keep insurance, property and estate documents separate from material approved for disposal.
A short written plan can bring the immediate tasks together:
- Confirm who can approve entry, repairs and clearance.
- Record the insurer’s vacancy terms and any written changes.
- Assign inspections, utility checks and responses to damage.
- Set out what stays, what can go and what needs a decision.
Keep the plan accessible to the landlord, agent and anyone completing visits. Include the next inspection date and outstanding repairs so the handover is clear.
If clearance or cleaning is needed, you can tell us about your property. We can agree the areas involved and what needs protecting before work begins.
Clearance doesn’t confirm insurance compliance or make a property ready to occupy. Those checks remain separate.
Frequently Asked Questions
When does a property count as unoccupied?
It depends on the definition in your policy and may depend on how long the property has been empty or whether it is furnished. Check the policy wording and schedule, and ask your insurer whether visits count as occupation.
How often should an empty property be inspected?
Follow the frequency and inspection requirements set out in your policy; another landlord’s timetable may not apply. Name someone to carry out the checks, arrange cover if they are unavailable and keep a record of each visit.
Do I need to tell my insurer before a property becomes empty?
Contact your insurer or broker as soon as you know a vacancy is likely. Give details of the expected duration, property condition, utilities, planned work and anyone who still has a right to occupy, and ask for any changes in writing.
Does unoccupied property insurance cover leaks, theft or renovation work?
Cover depends on the policy, its exclusions and any conditions attached to particular risks. Check escape-of-water, theft and renovation terms directly with the insurer before relying on cover or starting work.
Keep the vacancy manageable
Unoccupied property insurance and cover for property damage depend on the agreed terms and circumstances. Check the policy before the property becomes empty, then contact your insurer or broker if circumstances change.
Keep one clear record of inspections, access, utilities, repairs and approved work. Name the person responsible for each task.
You don’t need to resolve every property decision at once. Start with safe access, confirmed insurance requirements and the next inspection date.
